Laser Technology Market Size, Share, Trends & Forecast 2026-2034
22 Oct, 2026
8 Views 0 Like(s)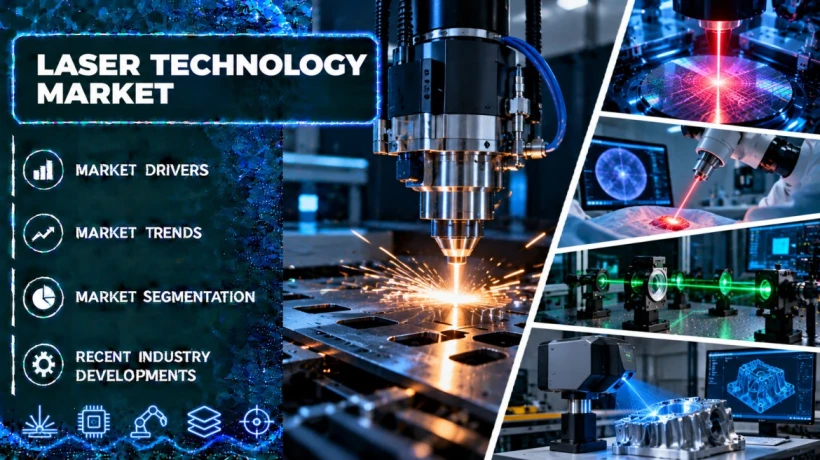
The laser technology market size increased from USD 20.52 Billion in 2025 to USD 21.99 Billion in 2026, and is expected to reach USD 38.16 Billion by 2034, at a CAGR of 7.13% during 2026-2034.
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the laser technology market. The global laser technology market grew from USD 20.52 Billion in 2025 to USD 21.99 Billion in 2026. Looking forward, IMARC Group estimates the market to reach USD 38.16 Billion by 2034, exhibiting a CAGR of 7.13% from 2026-2034, reflecting a strong growth trajectory. Growth is driven by rising demand for precision manufacturing and automation, expanding fiber-optic communication networks, the rapid adoption of laser welding in electric vehicle production, and continuous investment in ultrafast, compact and high-efficiency laser modules worldwide.
The market is witnessing steady expansion as lasers move from specialized equipment to core production infrastructure. Automotive, aerospace, electronics, semiconductor and healthcare manufacturers increasingly need non-contact processing that delivers tight tolerances, minimal material waste and repeatable quality at scale. At the same time, minimally invasive surgery, personalized consumer products and sustainable packaging are opening application areas that did not exist at commercial scale a decade ago. Asia Pacific holds 35% of the global market, supported by dense manufacturing ecosystems for automotive, electronics and semiconductors.
How AI is Reshaping the Future of the Laser Technology Market
- AI-Powered Process Monitoring and Adaptive Beam Control: Machine learning is being embedded in laser cutting and welding systems to monitor melt pools, seam quality and spatter in real time and adjust power, speed and focus on the fly. This cuts scrap and rework in high-value applications such as EV battery tabs, aluminum body structures and aerospace components. Product launches from laser makers in September and October showcased process-monitoring software designed to detect weld defects as they form.
- Predictive Maintenance and Laser Source Lifecycle Management: AI-driven analytics track diode degradation, thermal drift and optics contamination to predict failures before they halt a production line. For manufacturers running multi-shift operations, this reduces unplanned downtime and extends the working life of high-power fiber and solid-state sources.
- Generative Design and Smart Additive Manufacturing: AI tools optimize scan paths, power profiles and support structures for laser-based additive manufacturing, helping aerospace, medical implant and tooling producers move from prototype to certified production faster, with fewer failed builds and more consistent part density.
Grab a sample PDF of this report: https://www.imarcgroup.com/laser-technology-market/requestsample
Laser Technology Market Trends and Drivers
The global laser technology market is experiencing strong growth momentum, fueled by the convergence of manufacturing automation, electrification, high-speed data infrastructure and medical innovation. Laser processing is the leading application with a 44% share, covering cutting, welding, drilling, marking, engraving and additive manufacturing. Industrial users are the largest end-user group at 32%, because lasers deliver speed and precision that mechanical tools struggle to match, particularly on thin metals, advanced alloys and composites.
Electric vehicle production is one of the most tangible demand engines. Battery cells, busbars, motor hairpins and lightweight aluminum structures all depend on laser welding for strong, low-heat-input joints. This is why laser makers are launching application-specific tools for battery manufacturing. In April, nLIGHT introduced welding-focused solutions for battery production at The Battery Show North America, including its WELDForm and APT products, and in September and November it launched its nfinity and ProcessGUARD offerings for fabrication and sheet-metal customers at FABTECH and EuroBLECH. In November, Exail launched an Er:Yb co-doped fiber for fiber lasers capable of 30W output, strengthening the component base for high-performance fiber laser designs.
Optical communications is another powerful driver. Fiber-optic networks that carry data for cloud services, 5G backhaul and AI data centers rely on semiconductor and specialty lasers as their light source, and investment in network capacity continues to widen the demand base. Government programs are reinforcing this. The United States CHIPS and Science Act earmarked USD 52.7 Billion for domestic semiconductor manufacturing and research, and the European Chips Act mobilizes more than EUR 43 Billion in public and private investment. Both pull in laser-based lithography, annealing, inspection and micromachining equipment.
Personalization and sustainability add further momentum. Laser engraving of drinkware allows high-volume customization without inks or labels. In packaging, laser-based preform lightweighting for PET and rPET has reportedly cut preform waste by 50%, a clear example of how lasers support material-reduction goals. In medicine, thulium fiber lasers are gaining traction for lithotripsy and benign prostatic hyperplasia treatment, supporting the shift toward minimally invasive procedures with shorter recovery times. Medical training is expanding in parallel, with LA&HA, Fotona and Zaneo/Odella opening laser training centers in Bogotá and Mexico City.
Defence and public-sector programs are creating a high-value niche. Directed-energy systems and counter-drone lasers are being tested and deployed by several militaries. In April, India’s DRDO publicly demonstrated a vehicle-mounted 30 kW laser weapon that neutralized fixed-wing drones and surveillance sensors during trials. The UK government announced £500,000 for laser detection sensors designed to protect satellites. In the UAE, laboratory tests under the TII rain enhancement program in recent months showed that lasers can induce water vapor condensation, pointing to unconventional future applications.
Laser Technology Industry Segmentation
The report has segmented the market into the following categories:
Breakup By Type:
- Solid-State Lasers (Fiber, Ruby, YAG, Thin-Disk)
- Gas Lasers (CO2, Excimer, He-Ne, Argon, Chemical)
- Liquid Lasers
- Semiconductor Lasers
Solid-state lasers account for the largest type segment with a 40% share, driven by their efficiency, beam quality, compact form and low maintenance. Fiber lasers in particular have become the default choice for metal cutting, welding and marking across automotive, electronics and general fabrication.
Breakup By Product:
- Laser
- System
Standalone laser sources hold the largest product share at 65%, reflecting strong replacement and integration demand from machine builders, OEMs and system integrators.
Breakup By Application:
- Laser Processing (Cutting, Welding, Drilling, Marking, Engraving, Additive Manufacturing)
- Optical Communications
- Optoelectronic Devices
- Others
Laser processing leads with 44%, supported by factory automation and the need for flexible, contactless production methods.
Breakup By End User:
- Industrial
- Telecommunications
- Semiconductor and Electronics
- Commercial
- Aerospace and Defence
- Automotive
- Healthcare
- Others
The industrial segment holds the largest end-user share at 32%, driven by heavy use across metal fabrication, machinery, tooling and general manufacturing.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa (Saudi Arabia, UAE, Others)
Asia Pacific dominates the global laser technology market with a 35% share, supported by industrialization, extensive manufacturing infrastructure and strong demand from automotive, electronics and semiconductor producers. India is an emerging contributor, with clinics increasingly adopting domestically made “Make in India” medical lasers such as IMDSL’s dental and proctology systems. North America remains strong in industrial manufacturing, defence, healthcare and semiconductors, while Europe stands out as a mature, innovation-driven region with a deep R&D base.
Competitive Landscape
The report provides a comprehensive analysis of the competitive landscape in the laser technology market with detailed profiles of all major companies, including:
- Bystronic Laser India
- Coherent Corp.
- Epilog Laser
- Eurolaser GmbH
- Gravotech Engineering
- Han’s Laser Technology
- IPG Photonics
- Jenoptik AG
- LaserStar Technologies
- Lumibird Group
- Novanta Inc.
- Trumpf Group
Recent company activity shows how players are competing on application-specific solutions, regional reach and vertical integration. In January, Laser Technologies launched a 5-axis CNC tube bending machine and its Smart Weld Pro at IMTEX in Bangalore. Tescan acquired FemtoInnovations and established a laser business unit at UConn Tech Park. Civan Lasers opened two U.S. demo labs in Rexburg, Idaho and Detroit, Michigan, and Laser Photonics launched its CTIR-3060 pulsed fiber laser in recent months. Sichuan Strongest renewed its agent contract in South Korea, underlining the importance of local distribution.
What Does The Full Report Cover?
If you are tracking the laser technology market for investment decisions, market entry planning, competitive benchmarking or strategic advisory, IMARC Group’s report gives you everything in one place:
- Complete market sizing with revenue projections across the full outlook period
- Quantified growth driver analysis across type, product, application, end user and regional markets
- Sub-segment breakdowns for fiber, ruby, YAG, thin-disk, gas, liquid and semiconductor lasers with individual share data
- Country-level data for the United States, Canada, Germany, France, the United Kingdom, Italy, Spain, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico, Saudi Arabia and the UAE
- Competitive profiles of leading companies with strategic landscape assessment
- Latest innovation trends in ultrafast, high-power and compact laser modules
About Us
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
Comments
Login to Comment