How to Withdrawal From Fidelity 401k After Leaving a Job?
24 Oct, 2026
13 Views 0 Like(s)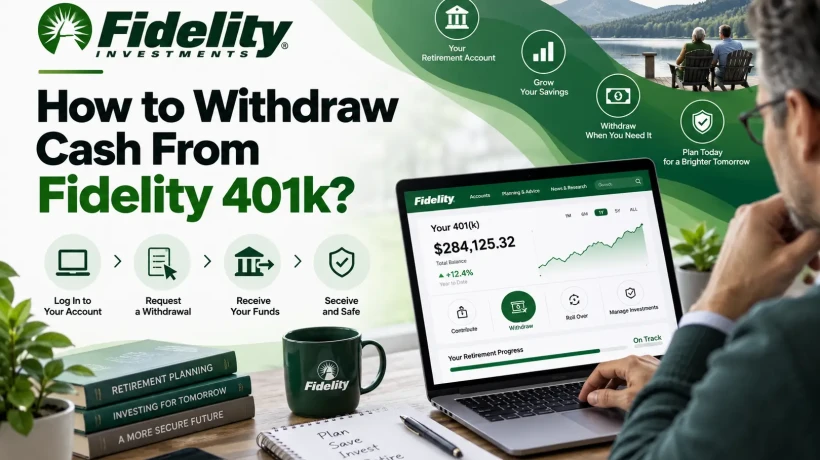
Learn how to withdraw from Fidelity 401k after leaving a job. Explore withdrawal steps, cash-out options, rollover rules, taxes, and penalties.
Leaving a job is a major career change, and managing your retirement savings is an important part of the process. If you have a retirement plan with Fidelity Investments, you may wonder what happens to your money and how to access it after leaving your employer.
A withdrawal from Fidelity 401k after leaving a job is generally possible once your employment separation has been processed. However, withdrawing retirement funds may involve income taxes, early withdrawal penalties, and other financial considerations.
Whether you want to cash out your retirement savings, transfer funds into a bank account, or move your balance into another retirement plan, understanding the available options can help you make an informed decision.
This guide explains how to withdraw money from Fidelity 401k after leaving a job, including eligibility requirements, online steps, taxes, and alternatives to withdrawing your savings.
Can You Withdraw From Fidelity 401k After Leaving a Job?
Yes, you can generally request a Fidelity 401k withdrawal after leaving your employer. Once your employment status is updated and your retirement plan permits distributions, you can access your eligible vested balance.
However, the amount available and the withdrawal process depend on your employer's retirement plan rules.
Important factors include:
-
Your age when leaving the employer.
-
Your available vested retirement balance.
-
Your former employer's distribution rules.
-
Outstanding 401k loans.
-
Federal and state income tax requirements.
-
Potential early withdrawal penalties.
A Fidelity 401k withdrawal after leaving employer does not automatically mean you must cash out your savings. You may also have options to keep your money invested or transfer it to another retirement plan.
According to Fidelity's guidance on leaving a job, employees generally have four options for their retirement savings.
How to Withdraw Money From Fidelity 401k After Leaving a Job?
If you are wondering how to withdraw cash from Fidelity, the process typically begins through Fidelity NetBenefits, the platform used to manage many employer-sponsored retirement plans.
Step 1: Log In to Fidelity NetBenefits
Visit the official Fidelity NetBenefits website and sign in with your registered credentials.
Locate the retirement plan associated with your previous employer.
Step 2: Check Your Available 401k Balance
Review your vested balance and confirm that Fidelity has received your updated employment status.
Your available withdrawal amount may differ from your total balance if some employer contributions are not vested or if other plan restrictions apply.
Step 3: Find the Withdrawal Options
Navigate to the section for loans, withdrawals, or distributions.
Look for an option related to taking money out of your retirement plan. The available menu and options depend on your specific plan.
Step 4: Select Your Withdrawal Type
Depending on your eligibility, you may be able to choose:
-
A full 401k cash-out.
-
A partial withdrawal.
-
A direct rollover to an IRA.
-
A rollover to another employer's eligible retirement plan.
Review the tax implications before selecting a withdrawal.
Step 5: Choose a Payment Method
For a cash withdrawal, Fidelity may offer payment by electronic bank transfer or check, depending on your plan.
Confirm your banking information and review the available delivery options.
Step 6: Review and Submit Your Request
Before submitting your Fidelity Investments 401k withdrawal request, carefully check:
-
Withdrawal amount.
-
Tax withholding.
-
Payment destination.
-
Estimated processing information.
-
Any required documentation.
Submit your request and save the confirmation for future reference.
Step 7: Track Your Withdrawal Status
After submission, check NetBenefits for status updates. Processing times can vary depending on plan requirements, payment methods, and verification procedures.
If the online option is unavailable, contact Fidelity through the official support information shown in your NetBenefits profile.
What Are Your Fidelity 401k Options After Leaving a Job?
Withdrawing 401k after leaving job Fidelity retirement benefits involves more than simply cashing out the balance.
You generally have four possible choices.
1. Leave Your Money in Your Previous Employer's Plan
If your former employer's plan permits it, you may keep your retirement savings invested.
This allows your money to remain in a tax-advantaged retirement plan, although investment choices and fees depend on the plan.
2. Roll Over Your Fidelity 401k Into an IRA
A direct rollover from a traditional 401k to a traditional IRA generally allows you to move eligible retirement savings without immediate income taxes.
A Fidelity IRA withdrawal made later follows IRA-specific tax and distribution rules, which may differ from those applicable to a 401k.
3. Transfer Your Savings to a New Employer's 401k
If your new employer's retirement plan accepts rollovers, you may transfer your eligible balance into that plan.
This option can make managing retirement savings easier by keeping them together.
4. Cash Out Your Fidelity 401k
A Fidelity 401k cash-out provides access to your retirement savings.
However, the taxable portion of your withdrawal is generally subject to income taxes. If you withdraw before age 59½, an additional 10% early distribution tax may apply unless you qualify for an exception.
Fidelity 401k Early Withdrawal Rules and Penalties
Understanding the Fidelity 401k early withdrawal rules is essential before requesting a distribution.
Withdrawal Before Age 59½
If you take money from a traditional 401k before age 59½, the taxable amount generally becomes part of your annual income.
You may also owe an additional 10% early withdrawal tax.
For example, suppose you withdraw $10,000 from your traditional 401k at age 40.
If the entire amount is taxable and no exception applies, you could owe:
-
Ordinary income taxes on $10,000.
-
An additional $1,000 early withdrawal tax.
-
Any applicable state income taxes.
The Age 55 Exception
An important exception applies when you leave your employer during or after the calendar year you turn 55.
Eligible distributions from that employer's qualifying retirement plan may avoid the additional 10% early withdrawal tax.
This exception generally does not apply to IRA withdrawals.
The IRS retirement age guidance explains these rules.
Withdrawal After Age 59½
Once you reach age 59½, eligible retirement distributions generally avoid the additional 10% early withdrawal tax.
However, regular income taxes may still apply to traditional 401k withdrawals.
How Much Tax Will Fidelity Withhold From a 401k Withdrawal?
Tax withholding depends on the type of distribution.
For most taxable 401k distributions eligible for rollover but paid directly to you, federal rules generally require 20% withholding.
For example, if you request a $20,000 eligible cash distribution, $4,000 may be withheld for federal taxes, leaving $16,000 before any other withholding.
This withholding is not necessarily your final tax bill. Your actual tax liability depends on your income and circumstances.
A direct rollover to an eligible retirement plan generally avoids mandatory federal withholding.
Can You Withdraw Fidelity 401k Without a Penalty?
Yes, certain circumstances may allow an early distribution without the additional 10% tax.
Possible exceptions include:
-
Qualifying separation from employment at age 55 or older.
-
Certain qualifying disabilities.
-
Specific medical expenses.
-
Qualifying substantially equal periodic payments.
-
Other exceptions recognized by the IRS.
A Fidelity emergency withdrawal may qualify for special treatment under certain federal provisions and plan rules. However, not every financial emergency qualifies.
Similarly, a Fidelity first time home buyer 401k withdrawal is not automatically exempt from the 10% additional tax. The special first-time homebuyer exception generally applies to qualifying IRA distributions, not ordinary 401k cash withdrawals.
Review the IRS early distribution exceptions before proceeding.
Fidelity Individual 401k and Self-Employed Plans
People searching for Fidelity Individual 401k, Self Employed 401k Fidelity, or Personal 401k Fidelity may have a different retirement arrangement from an employer-sponsored plan.
An individual 401k is typically designed for eligible self-employed individuals and business owners.
The rules for taking distributions from these plans can depend on the plan documents, the business owner's employment circumstances, age, and other qualifying events.
Always confirm the specific requirements before requesting a withdrawal from Fidelity.
Common Problems When Withdrawing From Fidelity 401k
Sometimes a Fidelity 401k withdrawal online request cannot be completed immediately.
Common reasons include:
-
Your employer has not updated your separation status.
-
Required verification is incomplete.
-
The retirement plan has distribution restrictions.
-
You have an outstanding retirement plan loan.
-
Your payment details require confirmation.
If you experience a problem, review the notices in your Fidelity NetBenefits profile or contact the retirement plan support team.
Avoid submitting duplicate withdrawal requests while your original transaction is being processed.
FAQs
1. How do I withdraw money from Fidelity after leaving my job?
Log in to Fidelity NetBenefits, select your former employer's retirement plan, review the available withdrawal options, and follow the instructions to request a distribution. The process depends on your plan's rules.
2. Can I cash out my Fidelity 401k after quitting my job?
Yes. You can generally cash out your eligible vested balance after leaving your job. However, income taxes and possible early withdrawal penalties may apply.
3. How long does a Fidelity 401k withdrawal take?
Processing times vary based on your employer's plan, verification requirements, and chosen payment method. Check your NetBenefits account for available processing estimates.
4. Can I withdraw from Fidelity 401k without paying taxes?
A direct rollover to an eligible traditional IRA or qualified retirement plan generally does not trigger immediate federal income tax. However, cash withdrawals of pretax funds are generally taxable, even when the 10% early withdrawal tax does not apply.
5. Can I transfer my Fidelity 401k to a bank account?
Yes, if your plan allows a cash distribution and supports electronic payment. You must first request an eligible withdrawal and provide the required bank information.
6. What happens if I leave my Fidelity 401k with my previous employer?
Your savings may remain invested in the previous employer's retirement plan if the plan allows it. Smaller balances may be subject to mandatory distribution or automatic rollover rules.
Conclusion
A withdrawal from Fidelity 401k after leaving a job can provide access to your retirement savings, but it is important to understand the rules before taking action.
You can generally request an eligible withdrawal through Fidelity NetBenefits after your employment separation has been processed. However, cashing out may trigger income taxes and early withdrawal penalties.
If you do not need the money immediately, consider whether keeping your funds invested or completing a direct rollover better supports your retirement goals.
Before making a final decision, review your employer's retirement plan documents, confirm your eligibility, and understand the potential tax consequences.
Comments
Login to Comment