How to Use the Receivable Turnover Formula to Improve Cash Flow
15 Sep, 2026
4 Views 0 Like(s)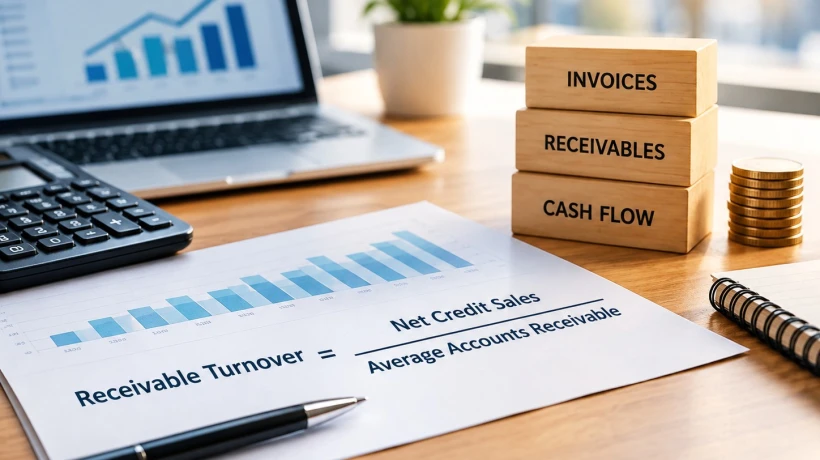
Learn how the receivable turnover formula works, how to calculate it, what the results mean, and how bookkeeping support can improve cash flow.
Getting paid on time is essential for any business. A company can have strong sales and still struggle financially if too much money is tied up in unpaid customer invoices. That is why understanding accounts receivable performance is an important part of financial management.
The receivable turnover formula helps business owners measure how effectively they collect money owed by customers. A higher turnover can indicate that invoices are being collected efficiently, while a lower result may point to delayed payments, weak credit policies, or collection problems.
Understanding this ratio is only the first step. Businesses also need accurate records, consistent invoice tracking, and reliable financial reporting to determine why receivables may be slowing down.
What Is Receivable Turnover?
Receivable turnover is a financial ratio that measures how many times a business collects its average accounts receivable during a specific accounting period.
In simple terms, it answers an important question:
How efficiently does the business turn credit sales into cash?
For businesses that sell products or services on credit, this measurement can provide useful insight into cash flow and customer payment behavior.
For example, a company may report $500,000 in credit sales during a year. If customers take too long to pay their invoices, the business may have difficulty covering payroll, supplier payments, operating expenses, or other financial obligations.
The turnover ratio can help identify this issue before it becomes a larger cash-flow problem.
Receivable Turnover Formula Explained
The basic formula is:
Receivable Turnover = Net Credit Sales ÷ Average Accounts Receivable
To calculate average accounts receivable:
Average Accounts Receivable = (Beginning Accounts Receivable + Ending Accounts Receivable) ÷ 2
Businesses generally use net credit sales rather than total sales because the ratio is intended to evaluate credit-based customer collections.
Example Calculation
Suppose a business has:
- Net credit sales: $600,000
- Beginning accounts receivable: $80,000
- Ending accounts receivable: $120,000
First, calculate average accounts receivable:
($80,000 + $120,000) ÷ 2 = $100,000
Then calculate turnover:
$600,000 ÷ $100,000 = 6
The business has a receivable turnover ratio of 6. This means its average accounts receivable was converted into collected sales approximately six times during the year.
However, the number should not be viewed by itself. Comparing it with previous periods and industry expectations provides much more useful information.
What Does a High Receivable Turnover Mean?
A relatively high ratio may indicate that customers are paying invoices promptly and the company has effective collection procedures.
This can support healthier working capital because less money remains outstanding for extended periods.
A strong turnover ratio may also suggest that the business has:
- Clear payment terms
- Effective invoicing procedures
- Consistent collection follow-ups
- Customers with reliable payment habits
- Appropriate credit policies
- Accurate accounts receivable records
Still, an unusually high ratio isn't automatically positive. Very restrictive credit terms could reduce sales opportunities, while aggressive collection practices could affect customer relationships.
The goal is not simply to maximize the ratio. The goal is to maintain a healthy balance between sales growth, customer relationships, and timely collections.
What Does a Low Ratio Tell You?
A declining turnover ratio deserves attention.
A low result can mean customers are taking longer to pay, invoices aren't being followed up consistently, or the business has accumulated older receivables.
Possible causes include:
- Late customer payments
- Incorrect or delayed invoices
- Disputed charges
- Weak credit screening
- Poor collection procedures
- Outdated customer records
- Cash-flow management issues
A lower ratio doesn't necessarily mean the business is performing poorly overall. It simply highlights an area that may require closer examination.
Turnover Ratio vs. Days Sales Outstanding
The receivable turnover ratio becomes even more useful when combined with Days Sales Outstanding (DSO).
DSO estimates the average number of days customers take to pay.
A commonly used calculation is:
DSO = 365 ÷ Receivable Turnover
Using the previous example:
365 ÷ 6 = approximately 61 days
That means the business is taking roughly 61 days, on average, to collect its receivables.
This can make the financial information easier for business owners to understand. Instead of seeing only a ratio, they can evaluate collection performance in terms of actual days.
Why Accurate Bookkeeping Matters
Financial ratios are only as reliable as the records behind them.
If credit sales are recorded incorrectly, invoices are missing, payments aren't properly applied, or accounts receivable balances contain errors, the resulting ratio may provide a misleading picture.
This is where professional bookkeeping can make a significant difference.
A certified bookkeeper can help maintain organized financial records, reconcile accounts, monitor outstanding invoices, and ensure transactions are recorded consistently. Accurate bookkeeping gives business owners better information for evaluating receivables and making financial decisions.
The role isn't simply about entering transactions. Good bookkeeping creates a dependable financial foundation for understanding how money moves through the business.
How to Improve Accounts Receivable Turnover
If your ratio is lower than expected, several practical steps may help.
Review Your Payment Terms
Make payment expectations clear before providing products or services on credit. State due dates, accepted payment methods, and applicable late-payment policies.
Send Invoices Promptly
Delayed invoicing can create delayed collections. Send accurate invoices as soon as practical after completing a sale or service.
Monitor Aging Reports
An accounts receivable aging report separates outstanding balances by age. Reviewing categories such as current, 30 days, 60 days, and 90+ days can help identify collection risks.
Follow Up Consistently
A simple, organized follow-up process can prevent overdue invoices from being forgotten.
Investigate Disputed Invoices
Sometimes customers don't pay because an invoice contains an error or doesn't match the agreed terms. Resolving these issues quickly can improve collection speed.
Compare Results Over Time
Calculate the ratio regularly instead of checking it only once a year. Comparing monthly, quarterly, or annual results can reveal whether collection performance is improving or deteriorating.
When Should a Business Get Professional Bookkeeping Help?
Growing businesses often have more invoices, customers, expenses, and financial transactions than owners can comfortably manage themselves.
If accounts receivable records are frequently behind, financial reports are difficult to understand, or overdue invoices aren't being monitored consistently, professional bookkeeping support may be worthwhile.
An experienced bookkeeper can help establish organized processes for recording sales, reconciling payments, tracking receivables, and preparing financial information.
That information can then help owners make better decisions about credit policies, customer accounts, and cash-flow planning.
Use the Formula as a Decision-Making Tool
The receivable turnover formula is more than an accounting calculation. It can serve as an early warning tool for cash-flow problems and collection inefficiencies.
The most useful approach is to calculate the ratio accurately, compare it with historical results, review related metrics such as DSO, and investigate the reasons behind significant changes.
When combined with accurate bookkeeping and regular financial reviews, receivables data can give business owners a clearer view of how efficiently sales are becoming actual cash.
Ultimately, healthy receivables management isn't about collecting money as quickly as possible. It's about creating a consistent process that supports predictable cash flow while maintaining positive customer relationships.

Comments
Login to Comment