From Customer Verification to Fraud Prevention: The New Era of AI in Middle Eastern Banking
29 Oct, 2026
10 Views 0 Like(s)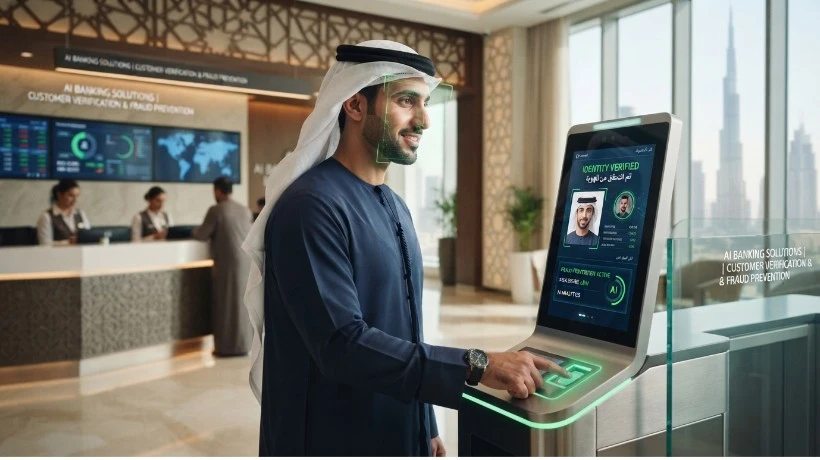
Discover how AI is transforming Middle Eastern banking, from faster customer verification to smarter fraud prevention and stronger digital trust.
A customer applying for a bank account expects the process to be straightforward. They want to submit their documents, complete verification and access their account without unnecessary delays. Behind the scenes, however, banks may need to check multiple records, verify identities, screen for risks and ensure every step meets regulatory requirements. When these tasks depend heavily on manual work, even a routine application can take longer than expected.
Across the UAE, Saudi Arabia, Qatar, Bahrain and other Middle Eastern markets, banks are looking for practical ways to improve these processes. Digital banking adoption, changing customer expectations and growing investment in financial technology are encouraging institutions to rethink how everyday operations are managed. Intelligent automation is emerging as one way to make banking workflows faster, more consistent and easier to manage.
Why Banks Are Rethinking Traditional Processes
Many banking activities involve repetitive steps that require employees to collect information, compare records, enter data and follow up on incomplete applications. These tasks are necessary, but they can consume time that teams could otherwise spend on customer service, investigations and complex financial decisions.
Technology can help streamline such work, provided it fits the bank's existing systems and operating procedures. For financial institutions working across multiple Middle Eastern markets, this also means accounting for different regulatory frameworks, customer identification requirements, languages and data protection obligations.
The aim is not to remove human judgement from banking. It is to reduce avoidable manual effort while giving employees better information and more time to handle situations that need their attention.
How Agentic Process Automation Can Improve Banking Workflows
Traditional automation is useful when a process follows a fixed sequence of rules. More complex tasks, however, may require information to be gathered from different systems, exceptions to be identified and the next action to depend on what has already happened.
This is where agentic process automation can become relevant. It combines AI agents with workflow tools to help coordinate multiple steps towards a defined outcome. Depending on the system's permissions, an agent might retrieve information, check whether documents are complete, prepare a summary and route an unusual case to the appropriate employee.
Consider a customer who submits a loan application with missing information. Instead of relying entirely on manual follow-ups, an automated workflow could identify the missing fields, prepare a request for the customer and update the application status. If the application raises a concern, it could be referred to a human reviewer.
Banks should define clear permissions and approval points before allowing agents to take action. Payments, lending decisions and other sensitive activities require particularly careful controls, monitoring and audit trails.
Intelligent Automation for Banks: Making Everyday Operations Easier
The value of intelligent automation for banks becomes clearer when it addresses a specific operational problem. Combining automation with AI capabilities can help institutions process documents, classify requests, extract information and direct work to the right teams.
For example, an operations team handling thousands of transaction records may spend considerable time identifying mismatches and investigating exceptions. Automation can compare records and highlight discrepancies, allowing employees to focus on resolving the cases that need attention.
Other useful applications include processing service requests, organising compliance documentation, supporting internal help desks and managing routine back-office activities.
For banks in Saudi Arabia and the UAE, these improvements can support digital transformation initiatives while helping teams manage increasing transaction volumes. Institutions should begin by identifying bottlenecks, measuring current processing times and testing whether automation produces meaningful improvements in accuracy, cost and turnaround time.
AI Fraud Detection in Banking: Finding Warning Signs Earlier
Fraud prevention remains an important priority as financial services become increasingly digital. Unusual transaction patterns, account takeover attempts, suspicious transfers and identity misuse can create risks for both customers and banks.
AI fraud detection banking solutions can help analyse transaction activity and identify patterns that may warrant investigation. Depending on the system, models can assess several signals together, flag unusual behaviour and help fraud teams prioritise cases for review.
For instance, a transaction that differs significantly from a customer's usual activity might be flagged for additional checks. The alert does not automatically prove fraud; it gives the bank an opportunity to investigate before deciding what action is appropriate.
Banks operating across the Middle East should evaluate detection systems against local transaction patterns, customer behaviour and applicable regulations. False positives also matter: repeatedly blocking legitimate transactions can frustrate customers and increase the workload for investigation teams.
Effective implementation therefore requires ongoing model testing, monitoring, secure data handling and clear procedures for reviewing alerts.
AI-Powered KYC and Onboarding: Reducing Friction for Customers
Opening an account can involve identity documents, address verification, customer information checks and risk screening. When each stage is handled separately, customers may have to wait for updates or submit information more than once.
AI-powered KYC and onboarding can help streamline these steps by extracting information from documents, identifying missing details and supporting verification workflows. Automated checks can also help route incomplete or potentially higher-risk applications for further review.
In the UAE, Saudi Arabia and other regional markets, banks must ensure that onboarding systems reflect the relevant country's identity verification, anti-money laundering and customer due diligence requirements. Arabic-language document handling and support for different document formats may also be important, depending on the customer base.
Automation should assist the verification process rather than bypass required checks. Final approval and escalation procedures should remain aligned with the institution's compliance framework.
Building a Practical Automation Strategy
Banks do not need to automate every process at once. A more manageable approach is to start with a high-volume task, establish a baseline and test the solution in a controlled environment.
Before implementation, decision-makers should consider:
-
Business impact: Identify processes where delays, errors or repetitive work create measurable problems.
-
Integration: Check whether the technology can work with existing banking platforms and approved data sources.
-
Security and compliance: Define access permissions, audit requirements, data handling rules and approval controls.
-
Performance: Measure accuracy, turnaround time, exception rates and customer experience.
-
Scalability: Assess whether a successful pilot can be extended to other departments or regional operations.
Technology providers and AI solution marketplaces can help banks explore relevant applications and assess their suitability for specific requirements. Redington AI Exchange, for example, provides a platform for discovering AI agents and enterprise solutions, including use cases relevant to banking and financial services.
For banks across the Middle East, the opportunity lies in using automation where it makes everyday banking more efficient without compromising trust, security or accountability. When implemented with clear objectives and appropriate oversight, intelligent systems can help employees work more effectively while giving customers a smoother banking experience.
Frequently Asked Questions
1. What is agentic process automation in banking?
Agentic process automation uses AI agents to coordinate multiple workflow steps, gather information and respond to defined conditions. Banks can use it to support operational processes while retaining human approval for sensitive decisions.
2. How does intelligent automation help banks?
Intelligent automation helps banks reduce repetitive manual tasks, process information more consistently, route exceptions and improve operational turnaround times. Its benefits depend on the quality of implementation and ongoing monitoring.
3. How is AI used for fraud detection in banking?
AI can analyse transaction patterns and other relevant signals to identify activity that differs from expected behaviour. These alerts help fraud teams investigate potential risks but do not independently establish that fraud has occurred.
4. Can AI-powered KYC and onboarding work across Middle Eastern markets?
Yes, these technologies can support document extraction, identity verification workflows and customer information checks. However, each deployment must account for local regulations, accepted identity documents, language requirements and data protection obligations.
Comments
Login to Comment