SoftPOS App for Women Entrepreneurs: Accept Payments, Build Business Confidence
06 Oct, 2026
7 Views 0 Like(s)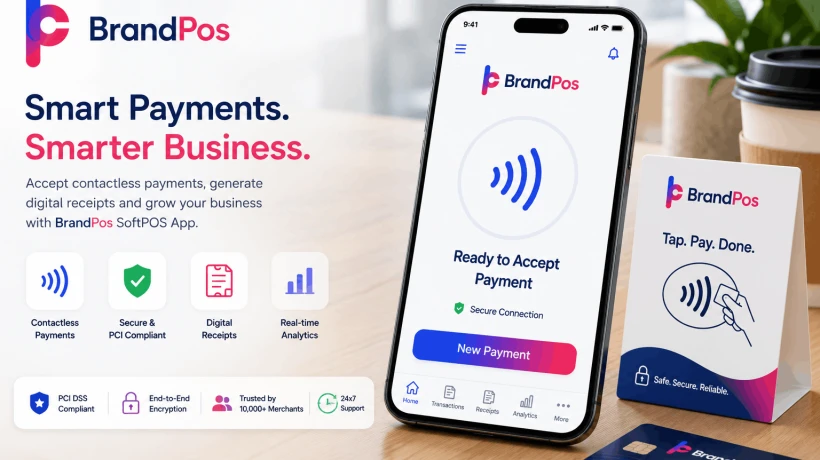
Discover how women entrepreneurs can accept professional digital payments with BrandPos, reduce hardware costs, build trust and grow flexible businesses.
Running a small business often means doing everything yourself. A home baker takes orders in the morning, prepares products in the afternoon and delivers them in the evening. A boutique owner manages customers, inventory and payments from the same shop. A tutor travels between students while an artisan sells products at weekend markets.
For these entrepreneurs, payment acceptance needs to be as flexible as the business itself.
A SoftPOS App allows eligible merchants to use a compatible smartphone for supported payment acceptance instead of investing in a separate payment terminal. That can make professional payment collection more accessible for women-owned businesses working from home, on the move or from small physical locations.
Why Payment Infrastructure Matters for Women-Owned Businesses
A professional payment experience can influence how customers perceive a business.
This does not mean that accepting cash makes a business less professional. Cash remains useful and familiar. But customers increasingly expect digital payment options, especially when purchasing higher-value products or services.
For a woman running a small business independently, the ability to accept payments through a smartphone can also remove one practical barrier to growth.
There is no need to create a dedicated checkout counter simply to accept a supported contactless payment. A phone can travel with the entrepreneur.
That flexibility is particularly useful when the business does not have a permanent retail location.
Women-Owned Business Types That Benefit Most from SoftPOS App
- Home bakers: Accept payment when delivering cakes, pastries or catering orders.
- Boutique owners: Take payments during private appointments, home visits or pop-up events.
- Tutors and coaches: Collect fees after sessions at the student's home or another location.
- Artisans: Accept payments at craft fairs, exhibitions and local markets.
- Freelancers: Collect payment after completing photography, design, consulting or creative work.
- Beauty professionals: Accept payments from clients after mobile appointments.
- Event professionals: Collect deposits and final balances at venues.
- Independent retailers: Add mobile checkout during busy periods without installing another fixed terminal.
The common factor is mobility. These businesses do not always operate from a traditional checkout counter.
A Smartphone Can Become the Payment Point
Many entrepreneurs already depend on their phones for business.
They use them to answer customer messages, manage social media, confirm orders, communicate with suppliers and track appointments.
Adding payment acceptance to an eligible device can therefore feel like a natural extension of existing business operations.
A SoftPOS App for Android can provide contactless payment functionality on compatible Android smartphones with NFC, subject to payment and device requirements.
That means an entrepreneur can potentially use an existing smartphone rather than purchasing a separate card reader.
The device still needs to meet applicable security and compatibility requirements. Rooted or modified phones may not be supported, and merchants should confirm device compatibility before relying on it for payments.
Digital Payments Can Build Customer Trust
Trust matters enormously for small businesses.
A customer buying a custom birthday cake from a home baker may have never visited a physical store. Someone ordering handmade jewelry from an independent artisan may be making a purchase entirely through social media.
A professional payment process can reinforce confidence.
Digital receipts provide customers with payment confirmation. Clear transaction records make it easier to answer questions later. Multiple payment options can also make the purchasing process more convenient.
The payment experience becomes another signal that the business is organized and ready to serve customers professionally.
How Digital Payments Help Women Entrepreneurs Grow Faster
- Make the business easier to buy from: Customers can choose a convenient supported payment method.
- Accept payments beyond a fixed location: Mobile acceptance follows the entrepreneur.
- Reduce dependence on cash: Businesses can avoid handling every payment physically.
- Create clearer records: Digital transactions are easier to review than scattered cash notes.
- Offer instant receipts: Customers can receive electronic payment confirmation.
- Support pop-up selling: Entrepreneurs can accept payments at markets, exhibitions and events.
- Add payment capacity as the business grows: Additional compatible devices can support staff or new locations.
- Improve customer confidence: A consistent payment process can reinforce a professional brand experience.
Growth is not caused by payment technology alone. Product quality, pricing, customer service, marketing and demand remain much more important. Digital payment infrastructure simply removes one potential source of friction.
The Cost Barrier Is Lower Than Traditional Hardware
For a new entrepreneur, every expense matters.
A dedicated POS terminal may require equipment purchase or rental, installation and ongoing maintenance. That can feel difficult to justify when the business is still testing demand.
BrandPos offers a free first month, according to its published pricing information, giving eligible merchants a lower-cost way to begin evaluating the platform.
Its Professional plan is listed at 0.19% per transaction with a €20 minimum monthly invoice. Pricing and plan terms should always be checked before making a purchasing decision.
The bigger advantage for many micro-businesses is that payment acceptance does not automatically require another piece of hardware.
PCI MPoC and Professional Payment Security
Professional payment acceptance also needs professional security.
BrandPos describes its platform as using payment security practices including encryption, tokenization and PCI-focused controls. Its SoftPOS approach is designed around industry payment security requirements, including the PCI Mobile Payments on COTS (MPoC) standard for applicable implementations.
This matters because entrepreneurs should not have to choose between convenience and security.
A home-based business may be small, but its customers still expect their payment information to be handled responsibly.
Merchants should also protect their own side of the system by keeping smartphones updated, using strong authentication and avoiding unofficial or modified software.
Women Entrepreneurs in Europe and the United States
The mobile-first model is not limited to one geography.
Women entrepreneurs across Europe and the United States operate businesses that involve home services, professional consulting, creative work, retail, events and mobile selling.
A smartphone-based payment model can be especially relevant where entrepreneurs need to meet customers outside a traditional store.
BrandPos is positioned for merchants in US and European markets, giving independent business owners an option for mobile payment acceptance where the service and relevant payment methods are supported.
The exact availability of features, payment methods, onboarding requirements and settlement arrangements can vary by country.
Women Entrepreneur Payment Options Compared
| Method | Professional Image | Setup Cost | Customer Trust | Receipt | Ease of Use | Business Growth Impact |
|---|---|---|---|---|---|---|
| Cash | Basic | Low | Familiar | Manual | Easy | Limited for remote records |
| UPI QR Manual | Professional | Low | High in supported markets | Digital/manual | Easy | Useful for local customers |
| Bank Transfer | Professional | Low | High | Digital | Moderate | Useful for higher-value payments |
| Payment Link | Professional | Low | High | Digital | Easy | Useful for remote orders |
| BrandPos SoftPOS App | Professional | No dedicated terminal required | High when supported | Digital options | Mobile | Flexible for in-person growth |
Each method serves a different purpose. A growing business may use several payment options rather than relying on only one.
A Home Baker in Germany
Consider a home-based baker in Germany who initially accepts mostly cash from local customers.
The baker begins delivering custom cakes to customers around the city. Some younger urban customers prefer paying by card rather than carrying cash.
The baker adopts BrandPos on a compatible Android smartphone and starts accepting supported contactless payments during doorstep deliveries.
Over the following months, the baker reports 40% monthly revenue growth as more urban card-paying customers begin ordering.
This is an illustrative scenario, not a verified BrandPos customer case study, and the 40% increase should not be interpreted as a guaranteed result of using the platform.
The payment system is only one part of the growth story. Better customer reach, product demand and convenient ordering could all contribute to increased revenue.
The useful lesson is simpler: when customers can pay using a method they already prefer, payment friction becomes less likely to interrupt the purchase.
From Side Business to Professional Operation
Many successful businesses start small.
A woman might begin baking from her kitchen, tutoring students after work or selling handmade products on weekends. At first, cash collection may seem perfectly adequate.
Then order volume increases.
Customers start asking for digital payments. Deliveries become more frequent. Business records become harder to manage manually.
That is when payment infrastructure starts becoming an operational issue.
A mobile solution allows the business to upgrade its payment experience without necessarily changing its entire operating model.
The entrepreneur can continue working from home, travelling to customers or attending events while carrying the payment capability with her.
Building Confidence Through Better Business Tools
Technology does more than process transactions.
For entrepreneurs building businesses independently, the right tools can create confidence in everyday operations.
A centralized transaction dashboard can make payment activity easier to monitor. Digital receipts can create clearer records. Multi-device support can help when employees or family members eventually assist with the business.
As the company grows, the payment system can grow with it.
That scalability is particularly useful for businesses that do not know how large they will become when they first start.
Final Thoughts
Women entrepreneurs do not need to wait until they have a large store, employees and multiple checkout counters before adopting professional payment technology.
A home baker, tutor, boutique owner, artisan or freelancer can start with the equipment already central to modern business: a smartphone.
BrandPos combines mobile payment acceptance with digital receipts, transaction visibility and security-focused payment infrastructure, while its free first month can reduce the initial barrier for eligible merchants.
The real value is flexibility.
Entrepreneurs can meet customers where they are, accept supported payments without carrying a dedicated terminal and build a payment experience that looks as professional as the business itself.
For a growing business, confidence often comes from removing small operational obstacles one by one. Payment technology can be one of them.
Frequently Asked Questions
1. Can a home-based business use BrandPos without having a physical shop?
Yes. BrandPos is designed for mobile payment acceptance, making it suitable for eligible businesses that operate from homes, customer locations, events or other temporary settings.
2. Does an entrepreneur need to buy a card reader for contactless payments?
No separate card reader is required for BrandPos's SoftPOS model. However, contactless tap payments require a compatible smartphone with NFC and supported payment functionality.
3. Is BrandPos suitable for a business with only a few transactions each month?
It can be considered, but merchants should compare the applicable pricing structure with their expected transaction volume. The Professional plan has a published minimum monthly invoice, so very low-volume businesses should evaluate the economics carefully.
4. Can women entrepreneurs use BrandPos outside their home country?
Availability depends on the market, merchant eligibility and supported payment infrastructure. BrandPos has a presence in US and European markets, but merchants should confirm service availability and payment-method support for their specific country.
5. Can a growing business add more payment devices later?
Yes. BrandPos supports multi-device management, allowing businesses to expand payment acceptance across compatible devices as their operations grow.
Comments
Login to Comment