India Cyber Insurance Market Size, Share Analysis, Growth Prospects and Forecast 2026–2034
21 Sep, 2026
8 Views 0 Like(s)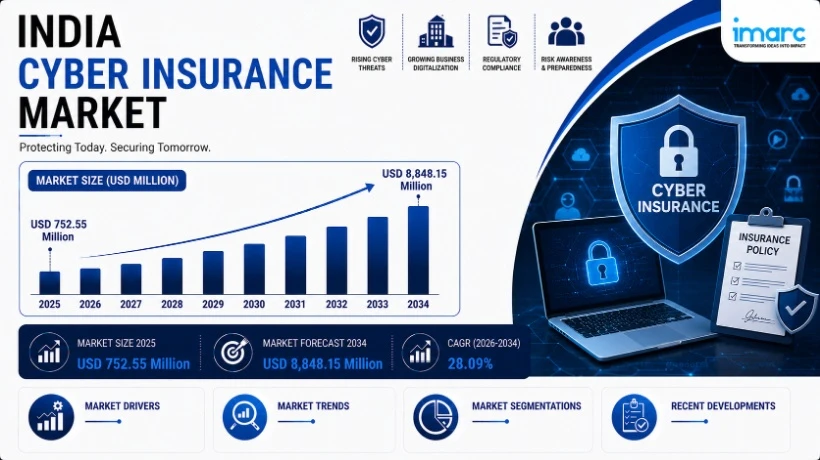
The India cyber insurance market size was valued at USD 752.55 Million in 2025 and is projected to reach USD 8,848.15 Million by 2034, growing at a compound annual growth rate of 28.09% from 2026-2034.
India Cyber Insurance Market: Comprehensive Outlook
The report titled "India Cyber Insurance Market Size, Share, Trends and Forecast by Component, Insurance Type, Organization Size, End-Use Industry, and Region, 2026–2034" comprises an extensive, deep-dive analysis of the Indian market. It covers precise market sizing, growth trajectories, macro-economic drivers, regional demand clusters, and other critical metrics defining the domestic digital risk management and liability ecosystem.
How Big is the India Cyber Insurance Market?
The India cyber insurance industry size was valued at USD 752.55 Million in 2025. Looking forward, IMARC Group expects the market to reach a massive USD 8,848.15 Million by 2034, exhibiting an exceptional compound annual growth rate (CAGR) of 28.09% during the 2026–2034 forecast period. The market is undergoing a profound structural evolution, transitioning from a niche IT procurement item into a non-discretionary, board-level pillar of corporate governance, driven by severe regulatory penalties and the escalating sophistication of ransomware cartels.
Emerging Trends in the India Cyber Insurance Market:
-
AI-Driven Continuous Underwriting: Indian insurers have moved completely away from static, annual risk questionnaires. By integrating API-led telemetry and External Attack Surface Management (EASM) tools, insurers now continuously monitor a client's network posture in real-time. If an enterprise leaves a critical cloud port open or fails to patch a known vulnerability, premiums adjust dynamically, or coverage is temporarily paused until remediation occurs.
-
Explicit Ransomware Extortion and Negotiation Coverage: Driven by sophisticated cyber-cartels targeting Indian healthcare and IT infrastructure, modern cyber policies are heavily prioritizing explicit "Ransomware Response" modules. These cover not just the potential ransom payment (where legally permissible), but critically, they deploy elite, pre-retained incident response teams to handle cryptocurrency negotiation, system decryption, and public relations crisis management.
-
Mandatory Incident Response (IR) Retainers: Insurers are shifting from mere financial indemnification to active risk mitigation. Many Tier-1 insurers now mandate that policyholders utilize the insurer’s approved panel of forensic investigators and technology lawyers during a breach. This ensures a standardized, rapid containment protocol, significantly reducing the ultimate financial payout required by the insurer.
-
Contingent Business Interruption (Supply Chain Risk): Following high-profile breaches originating from third-party IT vendors, large Indian enterprises are demanding "Contingent Business Interruption" coverage. This module protects the insured enterprise against financial losses and liability claims if their operations are halted due to a cyberattack on a critical cloud provider, payment gateway, or SaaS vendor.
-
Parametric Cloud Downtime Policies: Emerging specifically in the IT hubs of Bengaluru and Hyderabad, parametric policies are being structured around verified cloud outages. If a major public cloud provider (such as AWS or Azure) experiences an outage exceeding a predefined time limit (e.g., 4 to 8 hours), the policy automatically triggers a pre-agreed financial payout to the insured MSME without requiring a lengthy claims investigation.
Request Sample Report – TOC, Charts & Key Insights: https://www.imarcgroup.com/india-healthcare-it-market/requestsample
Growth Factors Driving the India Cyber Insurance Market:
-
The DPDP Act 2023 Enforcement Hammer: The strict operationalization of the Digital Personal Data Protection (DPDP) Act in 2025–2026 serves as the ultimate market catalyst. With the Data Protection Board authorized to levy massive fines—up to ₹250 crore per instance—for data breaches and failure to report incidents, corporate boards are aggressively procuring cyber insurance to transfer this unprecedented regulatory financial risk.
-
National Cybersecurity Budget Escalation: The Indian government practically doubled its cybersecurity budget from INR 400 Crore in 2023 to INR 759 Crore in 2024. This formal acknowledgment of the escalating threat landscape (highlighted by state-sponsored attacks on critical infrastructure) has cascaded into the private sector, validating board-level justifications for massive cyber insurance premiums.
-
Surge in Global Capability Centers (GCCs): India currently hosts over 1,900 GCCs, managing highly sensitive global IP, R&D data, and financial operations for Fortune 500 companies. These centers are bound by stringent global compliance laws (like GDPR and CCPA) inherited from their parent organizations, necessitating specialized, high-limit cross-border cyber liability policies written out of India.
-
SEBI and RBI Cyber Resilience Frameworks: The Reserve Bank of India (RBI) and the Securities and Exchange Board of India (SEBI) have issued stringent cybersecurity mandates for banks, NBFCs, and stockbrokers. These regulations require detailed incident reporting timelines and hold C-suite executives personally accountable, forcing the BFSI sector into the non-discretionary procurement of comprehensive cyber liability coverage.
-
The "Silent Cyber" Exclusion Squeeze: Historically, many enterprises relied on vague wording in their standard Commercial General Liability (CGL) or Property policies to cover cyber incidents (known as "Silent Cyber"). However, global reinsurers have aggressively mandated that primary insurers explicitly exclude cyber risks from standard policies. This forces enterprises to buy dedicated, stand-alone cyber policies to fill the sudden coverage gap.
How will the India Cyber Insurance Market Evolve in the Coming Years?
The India cyber insurance market is positioned for explosive, highly resilient expansion through 2034. It is transitioning from an optional IT procurement line item into a fundamental, non-discretionary pillar of Enterprise Risk Management (ERM).
The market generated a revenue of USD 752.55 Million in 2025 and is projected to reach an immense USD 8,848.15 Million by 2034, compounding at a staggering 28.09% annually. While large enterprises in the IT and BFSI sectors will maintain absolute volume dominance due to extreme regulatory exposure, the mid-market SME segment (driven by supply chain compliance) and AI-driven continuous underwriting models will dictate the fastest structural growth, optimizing loss ratios for domestic insurers.
Explore the Full Report with Charts, Table of Contents, and List of Figures: https://www.imarcgroup.com/india-healthcare-it-market
Industry Value Chain Analysis
-
Global Reinsurers: Giants (like Munich Re and Swiss Re) absorb the catastrophic systemic risk (e.g., a massive cloud outage affecting thousands of businesses simultaneously) and set the foundational pricing and capacity limits for the Indian market.
-
Primary Insurers & MGAs: Domestic general insurers (like ICICI Lombard, HDFC ERGO) and specialized Managing General Agents (MGAs) underwrite specific risks, issue policies, and collect premiums from Indian enterprises.
-
Cybersecurity Vendors & Telemetry: Tech companies providing the continuous monitoring platforms, external attack surface management (EASM) tools, and risk quantification software that insurers use to price the policies dynamically.
-
Insurance Brokers: The crucial intermediaries (like Marsh, Aon, and Willis Towers Watson) who translate complex IT risks into insurance terms, helping large enterprises negotiate bespoke coverage limits and policy wording.
-
Incident Response (IR) Panel: A pre-vetted network of digital forensic experts, ransomware negotiators, and specialized technology lawyers deployed instantly by the insurer the moment a client reports a breach to mitigate financial damage.
Deep-Dive Segment Insights
-
By Component: The market is bifurcated into Solution and Services. Solution dominates with a market share of 62.3% of the total India cyber insurance market in 2025.
-
By Insurance Type: Segmented into Packaged and Stand-alone. Stand-alone leads with a share of 65.2% of the total India cyber insurance market in 2025. S
-
By Organization Size: Divided into Small and Medium Enterprises (SMEs) and Large Enterprises. Large enterprises exhibit a clear dominance with a 68.4% share of the total India cyber insurance market in 2025.
-
By End-Use Industry: Spanning BFSI, Healthcare, IT and Telecom, Retail, and Others. IT and Telecom represent the leading segment with a 32.5% share of the total India cyber insurance market in 2025.
-
By Region: Geographically mapped across North India, West and Central India, South India, and East and Northeast India. South India prevails with a market share of 34.2% of the total India cyber insurance market in 2025.
Competitive Landscape & Key Company Insights
The Indian cyber insurance market exhibits a highly specialized, moderately concentrated landscape. It is dominated by major domestic general insurers heavily backed by global reinsurance capacity, specialized insurtech startups, and leading multinational insurance brokerages.
To defend market share and maintain profitability against surging ransomware claims, leading insurers are aggressively shifting from "passive indemnification" to "active risk management." They are mandating strict baseline cybersecurity controls—such as enforcing Multi-Factor Authentication (MFA), segregated offline backups, and Endpoint Detection and Response (EDR) implementation—before underwriting a policy. Insurers that successfully integrate real-time vulnerability scanning APIs into their pricing models are capturing the most lucrative, low-risk enterprise portfolios while minimizing their overall loss ratios.
Latest Recent Developments in the India Cyber Insurance Market (2025–2026)
-
Insurers Mandate Strict Baseline Security Controls (2025–2026): Responding to a massive spike in ransomware claims across the healthcare and IT sectors, major Indian general insurers structurally altered their underwriting guidelines. Throughout 2025 and 2026, it became an industry standard that corporate applicants will be outright denied coverage if they cannot definitively prove the deployment of Multi-Factor Authentication (MFA) across all remote access points, robust segregated backups, and active EDR systems.
-
Corporate Boards Drive DPDP Compliance Upgrades (2025–2026): Following the operational enforcement of the Digital Personal Data Protection (DPDP) Act, corporate boards across the BFSI and IT sectors mandated a total review of their cyber liability limits. Driven by the threat of ₹250 crore penalties, major brokers reported a massive surge in enterprises upgrading their stand-alone policy limits specifically to cover regulatory investigation costs and mandatory breach notification expenses.
-
Launch of Parametric Cloud Downtime Policies (Early 2026): Recognizing the systemic risk of IT concentration, specialized domestic MGAs and tech-focused insurers launched pilot parametric cyber policies heavily targeted at South India's startup ecosystem. These policies automatically trigger a predefined financial payout to the insured enterprise if a major cloud service provider experiences an unmitigated outage exceeding a set hourly threshold, entirely eliminating the need for a subjective claims investigation.
Customization Note: If you require any specific information not covered within this report’s scope, we will provide it as part of the customization.
Request Report Customization: https://www.imarcgroup.com/request?type=report&id=21304&flag=E
Frequently Asked Questions (FAQs)
- What is the size of the India Healthcare IT Market?
The India healthcare IT market size reached USD 26.60 Billion in 2026.
- What is the projected growth rate?
The market is projected to reach USD 112.09 Billion by 2034, exhibiting a massive compound annual growth rate (CAGR) of 19.70% during the forecast period from 2026 to 2034.
- Which component dominates the market?
Software captures the leading market share (48.3% in 2025), driven by the widespread institutional deployment of Electronic Health Records (EHR) and comprehensive hospital information systems.
- Which delivery mode is the most preferred?
Cloud-based delivery dictates the market (57.6% share in 2025), favored for its extreme operational scalability, seamless multi-hospital data synchronization, and elimination of heavy upfront hardware capital expenditure.
- Which region drives the most technology adoption?
North India commands the highest market share (31.2% in 2025), heavily anchored by a dense network of massive corporate hospital chains, elite public institutions, and strong central government IT procurement hubs across Delhi-NCR.
Comments
Login to Comment