India Solid Waste Management Market Size, Share, Outlook, Growth, Trends and Report 2026-2034
29 Sep, 2026
121 Views 0 Like(s)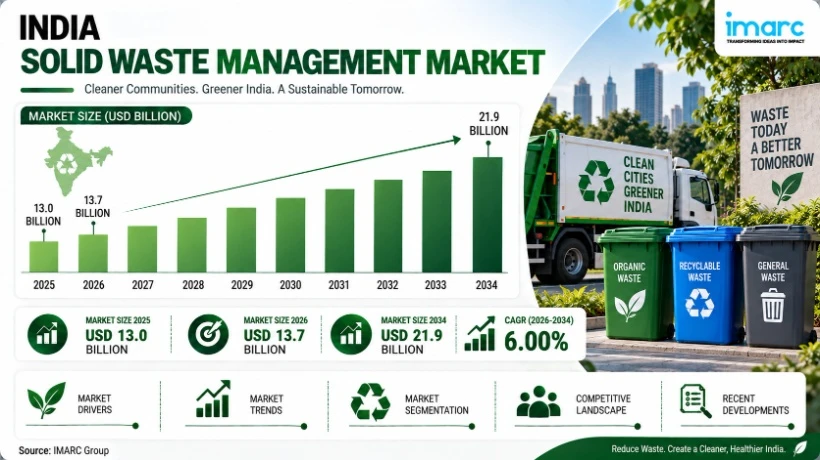
The India solid waste management market size increased from USD 13.0 Billion in 2025 to USD 13.7 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 21.9 Billion by 2034, exhibiting a growth rate (CAGR) of 6.00% during 2026-2034.
India Solid Waste Management Market: Industry Report 2026–2034
The India solid waste management market size increased from USD 13.0 Billion in 2025 to USD 13.7 Billion in 2026 and is projected to reach USD 21.9 Billion by 2034, exhibiting a compound annual growth rate (CAGR of 6.00%) during the 2026–2034 forecast period. The industry is expanding as cities, industries, and institutions seek more structured systems for collection, treatment, disposal, and recycling. Driven by rapid urbanisation, stricter environmental norms, rising municipal solid waste volumes, and growing emphasis on recycling and scientific disposal, solid waste management has become a critical public and industrial service across India.
What Is the Size and Growth Forecast of the India Solid Waste Management Market?
The market is exhibiting resilient, continuous expansion, fundamentally anchored by the escalating volume of municipal and industrial waste and the need for organised collection, safe disposal, and higher resource recovery.
- Market Size in 2025: USD 13.0 Billion.
- Market Size in 2026: USD 13.7 Billion.
- Market Forecast in 2034: USD 21.9 Billion.
- Compound Annual Growth Rate (CAGR): 6.00% during the 2026–2034 forecast period.
- Underpinning Momentum: Rising urban waste generation, expansion of formal collection systems, greater focus on recycling and scientific disposal, and regulatory pressure on municipalities and industries support steady long-term market growth.
What Are the Latest Emerging Trends in the India Solid Waste Management Market?
Strengthening of Formal Municipal Collection Systems:
Urban local bodies are progressively expanding door-to-door collection coverage and integrating private operators to improve efficiency and service reliability. Formal collection reduces open dumping and littering while creating a more consistent feedstock for treatment and recycling facilities. Technology such as route optimisation and vehicle tracking is being introduced in larger cities to lower costs and improve monitoring. As municipalities face higher waste volumes from growing populations, organised collection is becoming the foundation for any effective downstream processing and disposal strategy across residential and commercial areas.
Rising Emphasis on Recycling and Resource Recovery:
There is increasing recognition that landfilling alone is unsustainable. Municipalities and private players are investing more in material recovery facilities, composting, and recycling of plastics, paper, and other dry waste. Informal sector integration is also being explored to improve segregation and recovery rates. Brands and industries under extended producer responsibility frameworks are supporting collection and recycling of packaging waste. This shift toward circular approaches is gradually changing the service mix from pure disposal toward higher-value recycling and recovery activities.
Growing Attention to Industrial and Hazardous Waste Handling:
Industrial clusters and regulated sectors are under stronger pressure to manage hazardous and process waste through authorised channels. Scientific treatment, secure landfilling, and compliance documentation are becoming non-negotiable for many industries. Specialised service providers offering collection, transportation, and treatment of hazardous waste are expanding capacity. This segment demands higher technical standards and creates opportunities for organised players that can meet environmental clearances and provide reliable, compliant services to industrial end users.
Request a Sample Copy of this Report: https://www.imarcgroup.com/india-solid-waste-management-market/requestsample
What Growth Factors Are Driving the India Solid Waste Management Market?
Rapid Urbanisation and Rising Municipal Waste Volumes:
Expanding cities and higher consumption levels are generating significantly more municipal solid waste from households and commercial establishments. Municipalities must invest in collection fleets, transfer stations, treatment plants, and disposal sites to cope with daily volumes. This structural increase in waste generation creates sustained demand for both basic and advanced solid waste management services. As urban populations continue to grow, the need for scalable and reliable systems becomes more urgent, supporting long-term market expansion across residential and commercial end users.
Regulatory Push for Scientific Disposal and Compliance:
Environmental regulations and municipal solid waste rules require proper segregation, processing, and disposal rather than uncontrolled dumping. Landfill standards, authorisation requirements, and monitoring obligations push urban local bodies and industries toward organised service providers. Non-compliance risks penalties and public criticism, making professional waste management a necessity rather than an option. This regulatory environment underpins demand for collection, treatment, recycling, and compliant disposal services across municipal and industrial segments.
Increasing Focus on Recycling and Circular Economy Goals:
National and local agendas emphasising resource recovery, plastic waste management, and reduced landfill dependence encourage investment in recycling infrastructure. Extended producer responsibility frameworks further link brand owners to collection and recycling outcomes. As recovery targets rise, demand grows for sorting facilities, recyclers, and integrated service models. This policy and market direction supports a gradual shift in revenue toward recycling and value recovery alongside traditional collection and disposal activities.
Industrial Growth and Specialised Waste Streams:
Manufacturing, construction, and other industrial activities generate substantial quantities of non-hazardous and hazardous waste that require structured handling. Industries prefer specialised operators capable of providing compliant transportation, treatment, and documentation. Growth in industrial clusters therefore translates into demand for dedicated industrial and hazardous waste management services. This complements municipal waste demand and broadens the overall addressable market for organised solid waste management companies.
Government Initiatives Supporting India Solid Waste Management Market Growth
- Swachh Bharat and Urban Cleanliness Missions: National cleanliness programmes have elevated the priority of municipal solid waste collection, segregation, and processing, encouraging cities to improve service coverage and infrastructure.
- Municipal Solid Waste Management Rules and Guidelines: Regulatory frameworks set expectations for segregation, processing, and scientific disposal, pushing municipalities and operators toward formal and compliant systems.
- Plastic Waste and Extended Producer Responsibility Policies: Rules linking producers to end-of-life management of packaging strengthen collection and recycling value chains and support organised recovery activities.
- Support for Waste-to-Energy and Processing Infrastructure: Policy encouragement for composting, biomethanation, and other processing options helps cities move beyond pure landfilling where feasible.
What Are the Key Challenges Facing the India Solid Waste Management Market?
- Inadequate Segregation at Source: Mixed waste remains common in many areas, reducing the efficiency of recycling and processing facilities and increasing the burden on disposal sites.
- Infrastructure and Funding Gaps in Smaller Cities: While large metros have improved systems, many smaller urban local bodies still lack adequate collection fleets, plants, and sanitary landfills.
- Integration of the Informal Sector: Waste pickers play a major role in recovery but often operate outside formal systems. Designing inclusive models that improve livelihoods and efficiency remains complex.
- Public Awareness and Behaviour Change: Sustained citizen participation in segregation and responsible disposal is essential but uneven, affecting overall system performance.
Deep-Dive Segment Insights
The market is meticulously segmented to address diverse waste streams, service types, and end-user needs.
By Waste Type
- Municipal Solid Waste, Industrial Waste, Hazardous Waste, and Others: Municipal solid waste forms the largest volume base, while industrial and hazardous streams require more specialised and compliance-driven handling.
By Service
- Collection, Disposal, and Recycling: Collection remains foundational; disposal continues to handle residual waste; recycling is gaining importance as resource recovery and circular economy goals strengthen.
By End User
- Residential, Commercial, and Industrial: Residential and commercial sources drive municipal waste volumes, while industrial users generate demand for both general and hazardous waste management services.
By Region
- North India, South India, East India, and West India: Demand is present across all regions, with larger cities and industrial clusters accounting for higher service intensity and infrastructure investment.
Competitive Landscape & Key Player Positioning
The market research report has also provided a comprehensive analysis of the competitive landscape. Competitive analysis such as market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant has been covered in the report. Also, detailed profiles of all major companies have been provided.
Key players include:
- Large municipal solid waste collection and processing operators
- Specialised hazardous and industrial waste management companies
- Recycling and material recovery facility operators
- Technology and equipment providers supporting collection and treatment
- Other organised players active across collection, disposal, and recycling services in India
Recent Developments
- Ongoing 2025–2026: Urban local bodies continued expanding formal door-to-door collection coverage and engaging private operators to improve efficiency and accountability.
- Recycling Focus: Greater attention was given to dry waste recovery, plastic recycling, and material recovery facilities in line with circular economy and EPR-related expectations.
- Industrial Compliance: Industrial and hazardous waste generators increasingly relied on authorised service providers for compliant treatment and disposal.
- Infrastructure Push: Progressive cities invested in processing capacity and improved disposal practices to reduce dependence on unscientific dumping.
- Market Outlook: Urbanisation combined with regulatory pressure and recycling goals supports steady growth of India’s solid waste management market through 2034.
Note: If you require any specific information not covered within this report's scope, we will provide it as part of the customization.
Request Report Customization: https://www.imarcgroup.com/request?type=report&id=31521&flag=E
Frequently Asked Questions (FAQs)
Q1. What is the current size of the India solid waste management market?
The India solid waste management market size increased from USD 13.0 Billion in 2025 to USD 13.7 Billion in 2026.
Q2. What is the projected market size by 2034 and the growth rate?
The market is projected to reach USD 21.9 Billion by 2034, exhibiting a compound annual growth rate (CAGR of 6.00%) during the 2026–2034 forecast period.
Q3. Which waste types are covered in the market?
The market includes municipal solid waste, industrial waste, hazardous waste, and others.
Q4. Which services are analyzed?
Key services include collection, disposal, and recycling.
Q5. Which regions are included in the report?
The market is analyzed across North India, South India, East India, and West India.
Comments
Login to Comment