India School Market Size, Segmentation Analysis, Share, Growth Trends and Industry Forecast 2026–2034
02 Sep, 2026
421 Views 0 Like(s)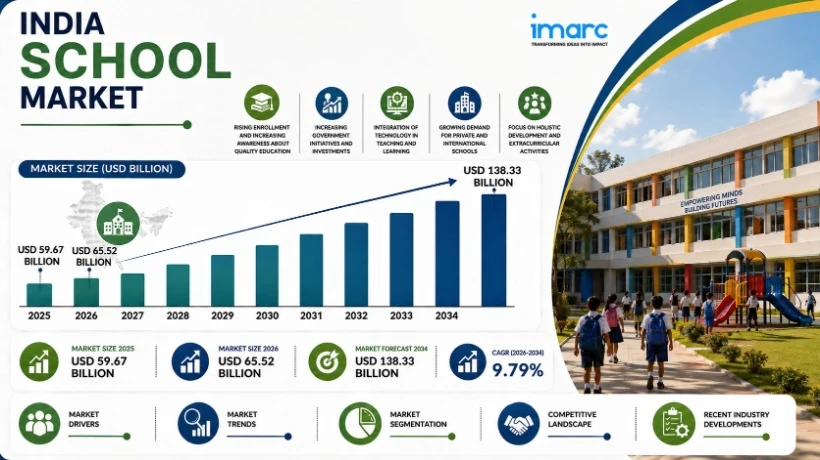
The India school market grew from USD 59.67 Billion in 2025 to USD 65.52 Billion in 2026 and is projected to reach USD 138.33 Billion by 2034, growing at a CAGR of 9.79% during 2026-2034.
India School Market: Industry Report 2026–2034
The India school market grew from USD 59.67 Billion in 2025 to an estimated USD 65.52 Billion in 2026 and is projected to reach USD 138.33 Billion by 2034, exhibiting a robust compound annual growth rate (CAGR) of 9.79% during the 2026–2034 forecast period. Encompassing one of the world's largest and most complex K-12 education systems, the Indian school market is undergoing a profound structural evolution. Driven by the mandates of the National Education Policy (NEP) 2020, massive digitalization efforts, and an unprecedented surge in parental aspirations, the sector is rapidly moving from rote-based learning toward experiential, technology-enabled, and globalized education paradigms.
What Is the Size and Growth Forecast of the India School Market?
The market is exhibiting highly resilient, continuous expansion, firmly anchored by India's massive demographic dividend and sustained public and private investments in K-12 educational infrastructure.
-
Market Size in 2025: USD 59.67 Billion.
-
Market Size in 2026: USD 65.52 Billion.
-
Market Forecast in 2034: USD 138.33 Billion.
-
Compound Annual Growth Rate (CAGR): 9.79% during the 2026–2034 forecast period.
-
Underpinning Momentum: The rapid expansion of premium international schools in urban centers, combined with massive government funding to modernize rural school infrastructure, ensures a continuous, high-volume capital injection into the sector.
What Are the Latest Emerging Trends in the India School Market?
-
Expansion of Premium Residential and International Schools:
There is a massive, growing demand from aspirational families, dual-income households, and NRIs for world-class schooling infrastructure. Educational institutions offering International Baccalaureate (IB) or Cambridge (IGCSE) curricula equipped with premium boarding, equestrian sports, and fine arts facilities are expanding rapidly across Tier-1 and Tier-2 cities, heavily backed by institutional private equity.
-
NEP 2020-Driven Foundational Learning Programs:
The National Education Policy (NEP) 2020 is fundamentally rewriting the early childhood curriculum. There is an aggressive shift toward play-based, activity-driven foundational learning for children aged 3–8 years. Schools are heavily investing in specialized early-educators, psychometric assessment tools, and interactive learning materials to meet these new compliance mandates.
-
Government Smart Classroom Rollout Under PM e-VIDYA:
State and central governments are actively bridging the digital divide. Through initiatives like PM e-VIDYA and Operation Digital Board, government schools are being rapidly modernized with internet-enabled smart boards, interactive flat panels, and localized digital curriculum delivery, vastly improving the quality of rural instruction.
-
Private School Chain Consolidation:
Organized private school networks are aggressively consolidating the highly fragmented unaided private school market. By utilizing franchise models and multi-city brand standardization, top private school chains are achieving massive economies of scale, allowing brand-conscious parents in Tier-2 and Tier-3 cities to access standardized, high-quality education at accessible fee points.
Grab a sample copy of this report: https://www.imarcgroup.com/india-school-market/requestsample
What Growth Factors Are Driving the India School Market?
-
India’s Massive Demographic Dividend:
India hosts the largest school-going population in the world. This immense base of K-12 students ensures a perpetual, high-volume demand for formal schooling infrastructure, teachers, and associated educational services across all economic strata.
-
Rising Household Prioritization of Education:
Across both urban and rural demographics, education is viewed as the primary vehicle for upward socioeconomic mobility. Consequently, household expenditure on education is rising disproportionately faster than income, with parents highly willing to invest in premium private schooling, extra-curricular coaching, and ed-tech supplements.
-
Universal Access Mandates and Government Funding:
Foundational legislation like the Right to Education (RTE) Act, combined with massive central funding schemes like Samagra Shiksha Abhiyan and the Mid-Day Meal scheme, guarantees sustained enrollment and retention rates in the dominant low-income and government school segments.
-
The Shift Toward Outcome-Focused Pedagogies:
Schools are actively transitioning from rote memorization to holistic, outcome-focused pedagogies. Institutions that successfully integrate STEM/STEAM labs, coding classes, and critical-thinking modules are witnessing massive enrollment surges, driving systemic structural upgrades across the competitive private landscape.
What Are the Key Challenges Facing the India School Market?
-
Severe Teacher Shortages and Quality Deficits:
While enrollment rates are high, the sector faces a massive shortage of qualified, adequately trained teachers, particularly in STEM subjects and special education. The disparity in teaching quality between elite urban private schools and rural government schools remains a critical bottleneck for holistic national development.
-
Regulatory Friction and Fee Caps:
Private unaided schools operate in a highly complex regulatory environment. Frequent state-level interventions regarding fee-cap regulations, stringent infrastructure mandates, and the complex reimbursement mechanisms under the RTE Act often strain the financial viability of mid-tier private institutions.
-
Infrastructural Disparities:
Despite government initiatives, a significant percentage of schools in deep rural pockets still lack basic functional infrastructure, including reliable electricity, clean drinking water, and separate sanitation facilities, leading to higher dropout rates among female students at the upper-primary levels.
Explore the Full Report with Charts, Table of Contents, and List of Figures: https://www.imarcgroup.com/india-school-market
Deep-Dive Segment Insights:
The market is meticulously segmented to reflect specific educational stages, operational ownership structures, and socio-economic demographics.
By Level of Education
-
Primary (42.0% in 2025): The absolute leading segment, representing the largest and most universally enrolled education tier in India. This dominance is heavily anchored by the Right to Education Act—mandating free and compulsory education for ages 6–14—and sustained public funding under the Samagra Shiksha scheme.
-
Upper Primary (24.6% in 2025): Reflects high enrollment maintained through critical state-sponsored retention programs, including midday meals and government scholarship schemes.
-
Secondary (19.8%) and Higher Secondary (13.6% in 2025): Show lower shares due to historical dropout rates linked to economic constraints. However, these represent high-growth opportunity segments as student retention improves under the NEP 2020 foundational and preparatory stage reforms.
By Ownership
-
Government (63.0% in 2025): The dominant ownership structure, holding the absolute majority enrollment share. This vast network functions as the backbone of literacy across India’s rural and semi-urban landscapes.
-
Private: A highly lucrative and rapidly growing organized sector, led by international franchise operators, corporate school chains, and technology-augmented private school networks.
By Board of Affiliation
-
State Government Boards (62.0% in 2025): The leading affiliation board, aligned with the massive government and state-aided school infrastructure catering to localized vernacular instruction.
-
CBSE, ICSE, and International Boards: Hold the remaining share, capturing the massive aspirational middle-class and elite demographic seeking globally recognized, standardized curricula.
By Fee Structure
-
Low-Income (56.0% in 2025): The undisputed market leader by volume, driven by India's extensive government school network providing free or nominally priced education to economically weaker sections. It reflects the market's fundamental structure as a predominantly public education system.
-
Medium-Income (28.4% in 2025): Captures the rapidly growing private school segment serving aspirational middle-class households seeking CBSE or state-board education at accessible fee levels.
-
High-Income (15.6% in 2025): Reflects premium private, international (IB/IGCSE), and elite residential school enrollment. It is the fastest-growing fee tier as urbanization, corporate education investments, and income growth aggressively expand the addressable premium market.
By Region
-
South India (32.0% in 2025): The leading region, driven by high literacy rates, highly proactive state education policies, a robust private school ecosystem, and significantly greater household spending on quality schooling (across Tamil Nadu, Karnataka, Kerala, Andhra Pradesh, and Telangana).
-
North India (26.5% in 2025): Driven by the sheer volume of the student population across Uttar Pradesh, Delhi, and Rajasthan, heavily supported by rapid private school expansion and CBSE dominance.
-
West and Central India (23.8% in 2025): Maharashtra and Gujarat drive massive premium school demand fueled by intense corporate school operator investments and urban middle-class income growth.
-
East India (17.7% in 2025): An emerging growth region. Increasing government investments under Samagra Shiksha and improving secondary school access in West Bengal and Odisha are rapidly narrowing historical infrastructure gaps and paving the way for private school penetration.
Competitive Landscape
The India school market’s competitive landscape is highly fragmented. While government-operated institutions hold the majority enrollment share by sheer volume, the organized private sector is intensely competitive, led by corporate school chains, international franchise operators, and tech-enabled networks expanding across metropolitan and tier-2 cities.
- K12 Techno Services Pvt. Ltd.
- VIBGYOR Group of Schools
- Ryan Group
- Pathways Schools
Recent Developments
-
2025 (Expansion of Corporate Ed-Tech Partnerships): K12 Techno Services actively scaled its technology integration across its campus network, heavily leveraging proprietary digital platforms to standardize teacher training and ensure uniform, high-quality curriculum delivery across its massive multi-city portfolio.
-
2025 (Premium Footprint Expansion): The VIBGYOR Group of Schools announced strategic expansions of its 'VIBGYOR Rise' brand, deliberately targeting aspirational Tier-2 cities to capture the surging demand for premium CBSE-affiliated schooling outside of traditional metropolitan strongholds.
-
2025–2026 (Government Digitalization Push): Following the continued rollout of the PM e-VIDYA scheme, multiple state governments achieved critical milestones in upgrading regional government schools with localized, vernacular digital content and smart-classroom hardware to align with NEP 2020 digital-first directives.
Customization Note: If you require any specific information not covered within this report's scope, we will provide it as part of the customization.
Request Report Customization: https://www.imarcgroup.com/request?type=report&id=1265&flag=E
Q1. What is the current valuation of the India school market?
The India school market grew from USD 59.67 Billion in 2025 to an estimated USD 65.52 Billion in 2026.
Q2. What is the projected growth rate for this sector?
The market is projected to reach USD 138.33 Billion by 2034, exhibiting a strong CAGR of 9.79% during the 2026–2034 forecast period.
Q3. Which educational level and fee structure command the highest market share?
-
Level: The Primary segment dominates with a 42.0% share (2025), supported by the RTE Act and universal enrollment mandates.
-
Fee Structure: The Low-Income segment leads the market with a 56.0% share (2025), fundamentally anchored by massive government schooling networks providing free or nominally priced education.
Q4. Who holds the majority ownership in the Indian school market?
The Government holds the absolute majority with a 63.0% share (2025) of school ownership, functioning as the primary provider of education across rural and semi-urban India. Accordingly, State Government Boards lead the affiliation segment with a 62.0% share (2025).
Q5. Which region dominates the India school market?
South India commands the highest regional market share at 32.0% (2025), heavily driven by strong state educational investments, high literacy rates, and a massive concentration of premium private schools in its metropolitan hubs.
Comments
Login to Comment